Epicor Has the Orders. Can Management See Which Ones Will Actually Make Money?
Revenue, schedule and shipment data are not enough to manage profitable manufacturing. Epicor users need a connected plan-to-profit view linking order promise, capacity, material, execution, job cost and margin before problems become month-end surprises.
The short answer
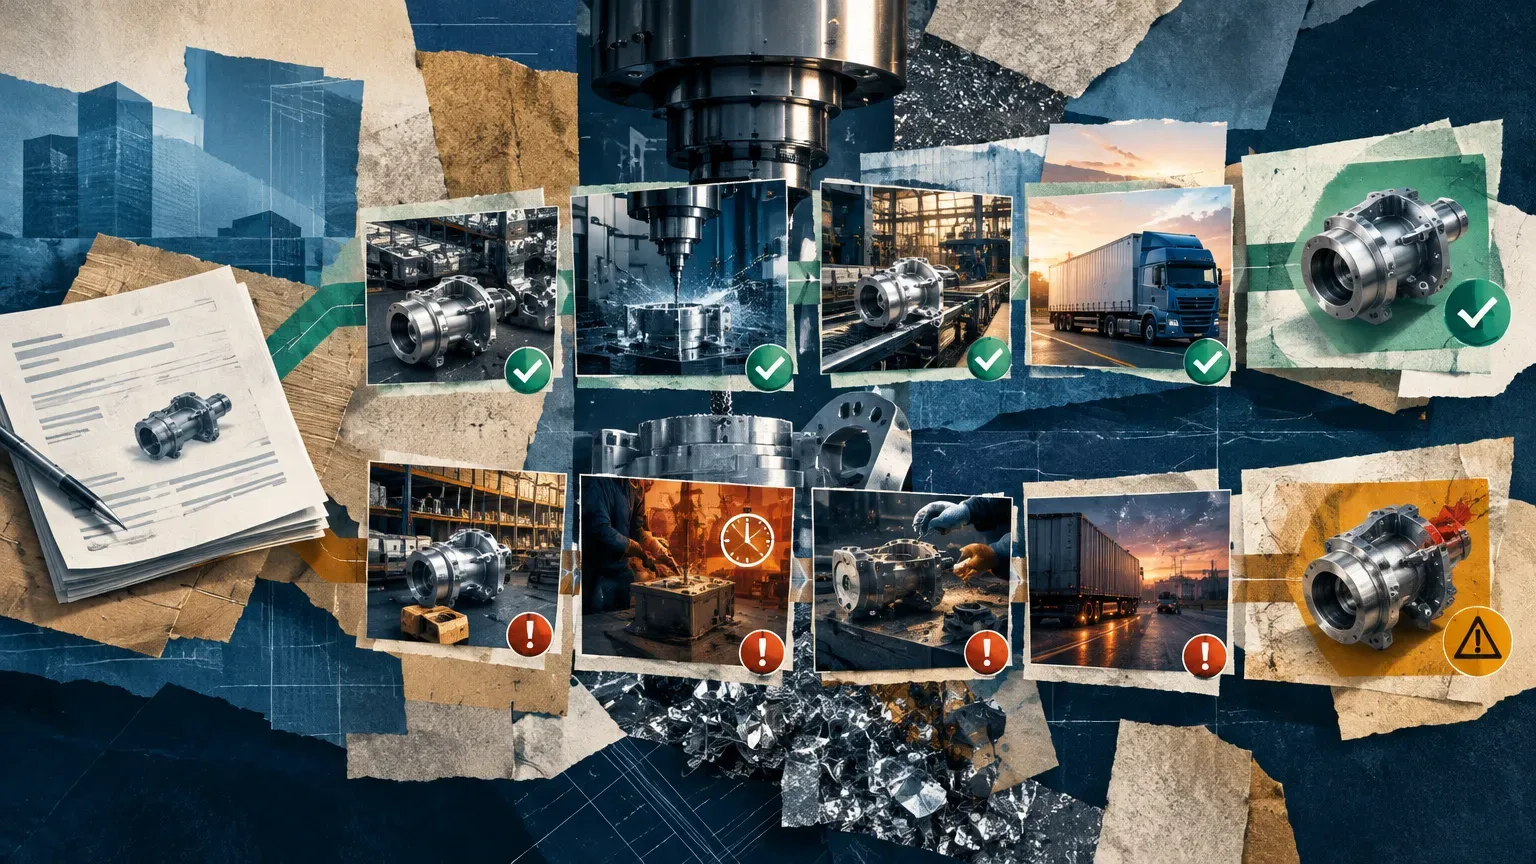
Epicor can contain the order, job, material, labour, shipment and financial transactions needed to understand manufacturing profitability, but management still needs an operating model that connects those facts before the month is over. An order that looks valuable when it is booked can become less attractive if the promised date forces overtime, critical material must be expedited, constrained capacity is displaced, engineering changes increase scope, scrap rises or job costs are reviewed only after shipment.
The useful management question is therefore not simply “What is our margin?” It is “Where between customer promise and final execution is expected margin changing, and can we see it early enough to act?”
A strong plan-to-profit model links six things: the customer promise, capacity, material readiness, schedule stability, job-cost variance and final margin. Those views should reinforce each other rather than live as separate reports.
Profitability starts before the job is released
Manufacturing margin is shaped by decisions made well before finance sees an actual cost.
Sales commits to a date. Planning decides where the work fits. Purchasing reacts to shortages. Operations absorbs changeovers and interruptions. Supervisors decide whether overtime is required. Engineering changes may alter materials or routing. Quality issues can create rework. Logistics may expedite a late shipment.
Each decision can be operationally reasonable and still change the economics of the order.
If management reviews profitability only after shipment, Epicor becomes a historical accounting system for margin rather than an operational tool for protecting it.
Separate booked revenue from executable revenue
A strong order book can create false comfort.
Two orders with the same selling value may carry very different execution risk. One fits available capacity, uses normal material supply and follows a stable routing. The other competes for a constrained machine, depends on long-lead material and requires a compressed delivery window.
The booked value does not show those differences.
Management should therefore distinguish between demand that is commercially booked and demand that can be executed under normal operating assumptions.
That does not mean refusing difficult orders. It means understanding which orders are consuming exceptional effort before that effort becomes invisible cost.
Make the customer promise operational
A promised date should be more than a field maintained by sales.
It should connect to what operations currently knows about:
- material availability;
- supplier lead time;
- constrained capacity;
- existing job load;
- routing duration;
- outside processing;
- quality or engineering dependencies;
- shipment requirements.
When those conditions change materially, the promise should become part of an exception conversation rather than remain untouched until the order is late.
The related article Sales Promised the Date. Can Epicor Show Whether Operations Can Actually Deliver It? explores how to make the customer date an operational commitment rather than a commercial assumption.
Capacity should be measured where it constrains delivery
Aggregate utilisation is often too broad to guide profitable decisions.
A plant can have spare labour or machine hours overall while one process remains the real constraint. If several important jobs compete for that same resource, management needs to know which orders will be delayed, which changeovers are avoidable and whether premium effort is justified.
The question is not “Are we busy?” It is “Which resource is deciding the delivery outcome?”
Your Schedule Looks Full. Which Epicor Jobs Are Consuming the Capacity That Matters? focuses on turning resource load into management evidence.
Released does not mean ready
A job can exist in Epicor, have a planned start date and still be impossible to execute.
One critical component may be missing. Material may exist but be allocated elsewhere. Stock may be in the wrong location. A supplier receipt may be expected but uncertain. Engineering or quality release may still be incomplete.
When planning treats released work as executable work, schedules fill with jobs that cannot start.
That creates unnecessary replanning and hides the real queue of work that can run now.
The Job Is Released. Why Is Production Still Waiting for Material? examines how to distinguish planned work from production-ready work.
Schedule changes have a cost
Rescheduling is sometimes necessary.
A customer escalates an urgent requirement. A machine fails. A supplier misses delivery. A quality issue blocks material. The operating model must adapt.
The problem is chronic rescheduling.
When priorities change every day, work in progress increases, supervisors lose confidence in the plan, material is staged for jobs that move again, changeovers multiply and expediting becomes normal.
A schedule is useful only if enough of it remains stable for operations to act on.
Production Is Busy. Why Does the Epicor Schedule Keep Changing Every Day? looks at how to manage schedule volatility as an operating problem rather than a planning inconvenience.
Review job cost while the cause is still visible
A variance discovered weeks after the job closed may be financially accurate but operationally weak.
By then the team may not remember why labour increased, why more material was issued, why subcontract cost changed or why the job required rework.
Cost variance creates more value when operations and finance can still connect the number to the event.
A useful review does not ask only whether the job was over or under budget. It asks which operational assumption changed and whether that cause is likely to repeat.
The Job Shipped. When Should Management Review the Cost Variance? focuses on making cost review timely enough to influence the next job.
Trace margin leakage through the lifecycle
Margin rarely disappears in one dramatic event.
It leaks through many smaller decisions:
- expedited freight;
- premium purchase price;
- extra setup;
- overtime;
- scrap;
- rework;
- engineering changes;
- additional subcontract work;
- unpriced customer requests;
- low-volume inefficiency;
- repeated schedule disruption.
The final margin may show the total effect, but management needs to connect the total back to its causes.
Revenue Is Up. Why Is Margin Still Leaking Between Quote, Job and Shipment? explores that quote-to-actual chain.
Build one management bridge from promise to profit
A plan-to-profit operating model does not require one giant dashboard.
It requires a consistent chain of questions.
1. What did we promise?
Identify the customer date, commercial assumptions and important service commitments.
2. Can we execute under normal conditions?
Check critical material, constrained capacity and other dependencies.
3. What changed after commitment?
Track shortages, priority changes, engineering changes, rework and other exceptions.
4. What did the change cost?
Connect material, labour, subcontract, freight and other costs to the operational event.
5. What happened to expected margin?
Compare the economics that supported the order decision with the actual execution result.
6. What should change next time?
Update planning assumptions, pricing logic, routing, sourcing, capacity decisions or customer terms where the pattern justifies it.
This bridge allows commercial, operational and financial teams to discuss the same order using different but connected evidence.
Avoid one universal profitability number
Different decisions need different views.
Sales may need expected margin at quotation or order acceptance. Operations may need job-level cost-to-complete risk. Finance may need actual recognized profitability. Management may need trend analysis by customer, product family or plant.
These views can coexist if their definitions and timing are explicit.
Problems arise when teams compare numbers built for different purposes and conclude that the ERP cannot be trusted.
The solution is controlled definitions, not forcing every user into one report.
Use exceptions to focus management attention
Most orders may follow the expected economics closely.
Management attention should concentrate on the orders where assumptions are moving.
Useful exception triggers may include:
- promised date at risk;
- critical material shortage;
- constrained-resource overload;
- repeated schedule movement;
- job cost above expected tolerance;
- abnormal scrap or rework;
- premium freight;
- unexpected subcontract variance;
- scope change without commercial recovery.
The thresholds should reflect the business.
The purpose is to make the few orders that need intervention visible without creating noise around normal work.
Connect commercial recovery to operational evidence
Sometimes margin erosion is unavoidable.
A customer changes scope. A rush request creates premium freight. A specification change requires rework. A late customer decision compresses the schedule.
If the operational cause is recorded clearly, the business has better evidence for repricing, change-order discussion or future contract terms.
Without that evidence, exceptional cost becomes an internal manufacturing problem even when the cause was commercial.
A plan-to-profit model therefore supports both cost control and stronger customer economics.
Make the operating model cross-functional
Profitability cannot belong only to finance.
Sales owns commitments and commercial terms. Planning owns assumptions about capacity and timing. Purchasing influences supply cost and risk. Operations owns execution discipline. Engineering can change routing or material. Quality affects scrap and rework. Finance interprets the final economic result.
The ERP connects these functions only if ownership of the business decisions is also connected.
A monthly margin report cannot substitute for cross-functional operating discipline.
What management should measure
Useful indicators include:
- orders with customer dates unsupported by current capacity or material;
- critical jobs released without full readiness;
- schedule changes after release;
- constrained-resource overload;
- premium purchase or freight cost;
- labour variance;
- material variance;
- scrap and rework cost;
- subcontract variance;
- jobs whose expected margin changed materially before shipment;
- completed jobs not reviewed within an agreed period;
- recurring margin leakage by cause.
The measures should help management intervene, not merely explain history.
A practical weekly plan-to-profit review
Choose the small set of open orders with the greatest combination of value, delivery risk and margin movement.
For each one, review the same sequence:
1. customer promise;
2. material readiness;
3. constrained capacity;
4. schedule change;
5. execution exception;
6. cost movement;
7. commercial recovery or management action.
Keep the discussion tied to evidence in Epicor and connected operational records.
Over time, recurring causes should become improvement themes rather than permanent agenda items.
ACC context
ACC supports Epicor environments across ERP implementation, process improvement and operational execution. The value of Epicor increases when commercial commitments, planning, shop-floor execution and financial results can be connected into one management conversation rather than reconciled after the fact. Explore ACC’s Epicor capabilities.
Keep one exception vocabulary across functions
Cross-functional profitability review becomes difficult when each team describes the same event differently.
Sales may call an order an expedite. Planning may call it a priority change. Operations may call it overtime. Finance may see only premium labour and freight.
Define a small shared set of causes so the chain can be traced from decision to cost.
The vocabulary does not need to replace detailed operational reasons. It needs to provide a common management layer.
Use historical evidence without planning by hindsight
Actual performance should improve future assumptions, but the organization should not simply copy last job's actuals into the next plan.
Separate unusual events from repeatable patterns.
If a job overran because of a one-time machine failure, updating the standard may make the next plan unnecessarily pessimistic. If five similar jobs all required more setup than planned, the evidence is stronger.
Use recurrence and cause before changing the baseline.
Connect working capital to the same model
Profitability is not the only consequence of weak planning.
Early material purchases, excess WIP, partial completion and delayed shipment can tie up cash even when the final margin remains acceptable.
A plan-to-profit review can therefore include selected working-capital signals where they influence management decisions.
This is especially useful when schedule instability causes material to arrive or work to start earlier than required.
Treat customer service as an economic outcome
On-time delivery and margin should not be managed as opposing goals.
Poor planning can damage both: the business incurs overtime and expedite cost yet still ships late.
The strongest operating model looks for decisions that protect service economically rather than choosing between customer and profit after the problem is already visible.
That is why promise, readiness, capacity, schedule and cost need to be reviewed as one chain.
Use profitability review to challenge assumptions before adding capacity
When margins weaken, management may conclude that the plant needs more equipment or labour. Sometimes that is correct. But a plan-to-profit review may show that avoidable schedule churn, low material readiness, inaccurate setup assumptions or unpriced expedite work is consuming existing capacity.
Before committing capital, test whether the constrained economics are structural or created by process instability.
If the same product family is consistently profitable only when overtime and premium freight are ignored, the commercial model may need attention. If the margin improves when schedule stability improves, the first investment may be operating discipline rather than equipment.
Make exceptions visible at order level
Plant-level cost trends are useful, but they can hide which customer commitments created exceptional work.
Where practical, connect major expedites, rework, scope changes and unusual labour to the order or job that caused them.
The purpose is not to allocate every overhead dollar with artificial precision.
It is to make material exceptions traceable enough that management can distinguish structural cost from customer- or order-specific disruption.
Frequently asked questions
Is profitability mainly a finance metric?
No. Finance measures the result, but many causes of margin movement originate in sales commitments, planning, purchasing and operational execution.
Should management review every job in detail?
Usually not. Use exception criteria to focus on high-value, high-risk or materially changed jobs.
Does a job need to be closed before cost variance is useful?
No. Interim variance can be valuable if the underlying transactions are sufficiently complete and the review purpose is clear.
Can better scheduling improve margin?
Yes, where schedule instability drives overtime, changeovers, expediting, rework or other avoidable execution cost.
What is the first step toward a plan-to-profit model?
Choose a small group of real orders and trace them from promise through capacity, material, execution, actual cost and final margin. The gaps will show where ownership or data is disconnected.