

One PO, Three Factories, Several Shipments. Can You Still See the True Order Margin?
Multi-factory execution and split shipments are normal in apparel, but they can fragment the economics of one customer order. The solution is controlled operational splitting with commercial consolidation.
The short answer
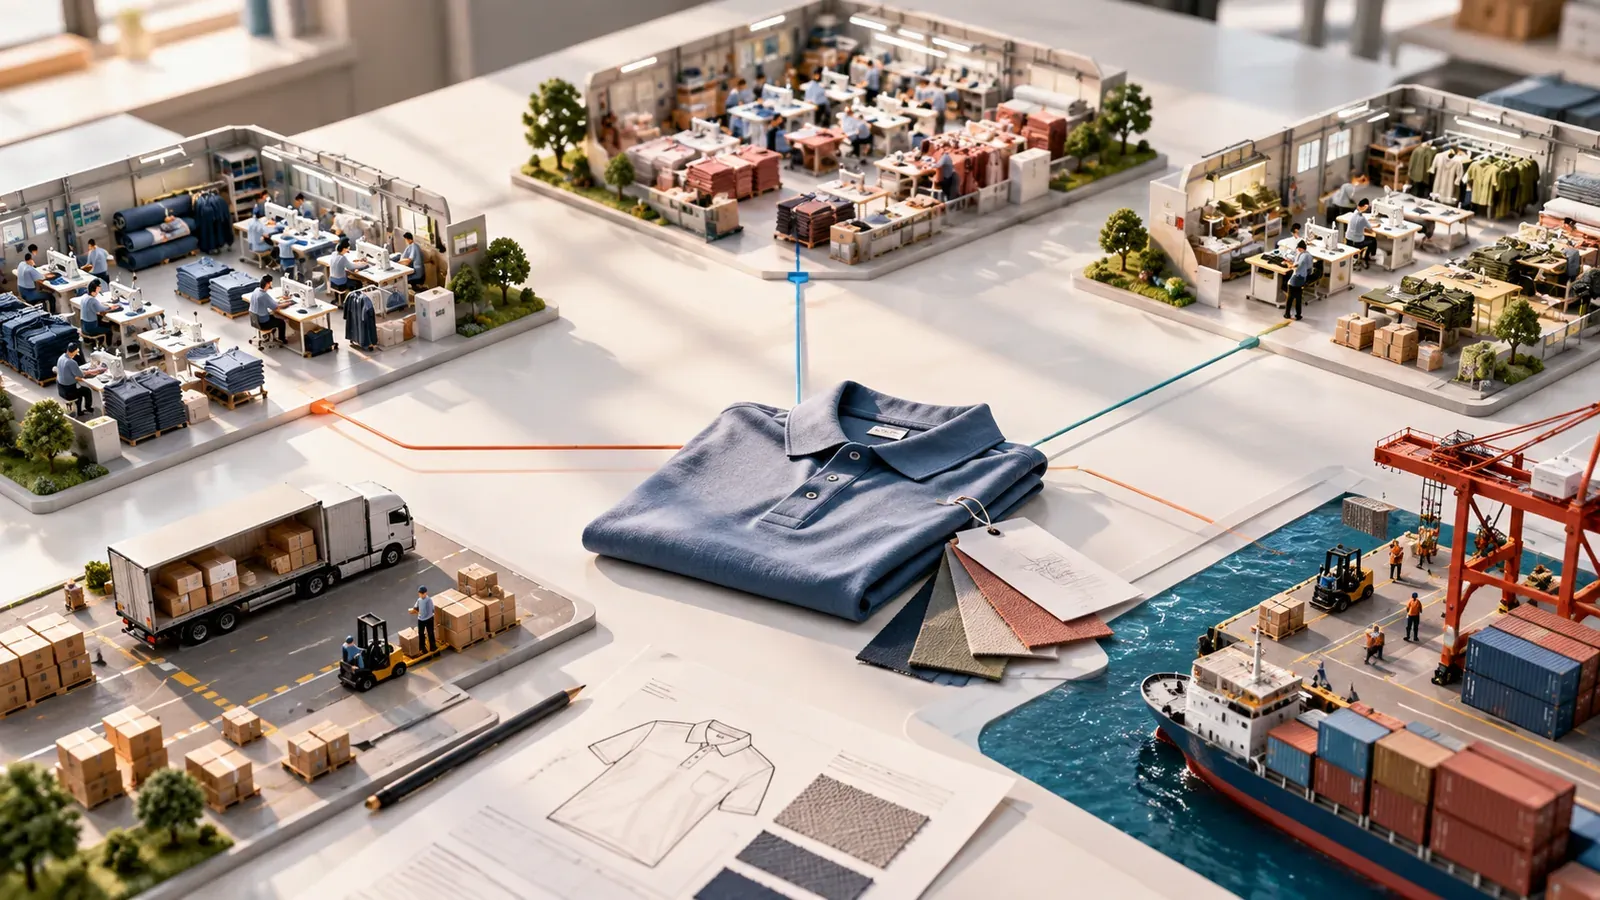
A customer PO can be split across factories and shipments without losing profitability visibility, but only if the commercial order remains the parent identity. Factory jobs, cut orders, subcontracting, inventory movements, packing lots, shipments and invoices can branch operationally; management reporting must still consolidate them back to the same order and style.
The mistake is allowing each operational split to become a separate economic story. When that happens, one site may look profitable because another site absorbed rework, one shipment may look clean because freight was posted centrally, and residual materials may sit outside the order that created them.
The need to recombine the order follows the same argument as From Confirmed Order to Final Margin: Where Does Garment Profitability Drift?: operational splitting should not fragment the commercial truth.
One customer order can fragment into many internal objects
Garment groups split orders for practical reasons:
- capacity is distributed across sites;
- one factory has specialist capability;
- material is available in different locations;
- delivery windows require parallel production;
- different destinations need separate packing and shipment;
- risk is balanced across factories;
- subcontracting is used for specific operations.
None of this is inherently a control problem. The challenge is preserving the relationship between the split objects and the original commercial commitment.
The customer order should remain the commercial parent.
The customer order should remain the reference for revenue, buyer terms, delivery commitment and consolidated margin.
Below it, operational objects can carry the detail needed by factories: site, job, color/size allocation, material reservation, routing, production quantity, packing and shipment.
A strong hierarchy lets management move in both directions:
- from customer order down to factory and shipment detail;
- from a factory cost or shipment charge back to the customer order.
If either direction is broken, reconciliation becomes manual.
Split execution should not erase the planned economics.
Before splitting the order, management should know the expected economics of each allocation.
That does not require a perfect transfer-pricing model. It does require enough structure to explain planned material, CM/labor, subcontracting and logistics by site.
This makes later variance analysis possible. Without a planned allocation, a high-cost factory cannot be distinguished from a factory that simply received the hardest part of the order.
Useful allocation dimensions include:
- style/color/size quantity;
- expected production minutes;
- material ownership and source;
- expected conversion cost;
- local subcontracting;
- packing/shipping responsibility;
- intercompany charges where relevant.
Material variance only makes sense when the sites come back together
Group-level inventory can create a false sense of sufficiency. One factory may have excess material while another buys urgently. Fabric transfers can also create additional logistics and handling cost.
The order-margin view should capture material usage and residuals across all sites, including transfers. Otherwise the final cost can be understated at one factory and overstated at another.
The management question is: what did the order consume as a group, regardless of where the material moved?
Split shipment can protect service while quietly changing freight economics.
A buyer may request partial delivery, or the company may split shipment to protect the earliest due date. Each shipment can carry different freight, documentation and handling cost.
If shipment cost is analyzed only per delivery, the business may miss the order-level effect of fragmentation.
The order view should distinguish planned versus actual shipment structure and show incremental cost created by splits, premium modes or late changes.
Cross-site traceability needs a shared order identity.
When materials, WIP or finished goods move between sites, the transfer should preserve order and lot identity. This supports both physical traceability and cost attribution.
The company does not need to use one specific standard internally, but it needs consistent identifiers so that a transfer does not create an orphan quantity.
Intercompany accounting is not the same as customer-order profitability
Multi-entity groups often use transfer prices or intercompany charges. Those are important for statutory and management accounting, but they can obscure the economic performance of the customer order.
A group-level profitability view should be able to eliminate or normalize internal charges and answer a simpler question: what external revenue did the order generate, and what real resources did the group consume to deliver it?
Both views can coexist:
- entity profitability for local management/accounting;
- customer-order profitability for group commercial decisions.
Partial completion can make one order look more finished than it is.
When one factory completes early and another is late, the order can sit in an ambiguous state. Some revenue may be invoiced, some material remains open, some WIP is still in production, and freight may already be incurred.
A useful order status should therefore distinguish:
- production completion by allocation;
- shipment completion by delivery;
- invoice completion;
- material closure;
- cost closure.
“Order shipped” is not always a single moment in a multi-site environment.
The useful management view recombines the order
For one multi-factory order, management should be able to see:
1. customer revenue and terms;
2. planned quantity by site;
3. actual produced/shipped quantity by site;
4. material usage and transfers;
5. labor/conversion cost by site;
6. subcontracting and rework;
7. shipment and logistics cost;
8. intercompany effects;
9. residual inventory or write-offs;
10. consolidated order margin.
If this requires offline spreadsheet merging every month, the operating data model is fragmented.
Where Epicor Venus keeps a split order commercially whole
Epicor provides the enterprise-grade ERP foundation for intercompany transactions, purchasing, inventory, finance and governance. Epicor Venus adds the garment-specific style, order, factory, production and shipment context needed to follow one customer commitment across multiple execution sites.
The objective is not to force every factory into one operational detail. It is to preserve enough common identity that material variance, production cost and shipment decisions can be consolidated back to the same customer order. ACC helps multi-factory garment groups design that balance around Epicor and Epicor Venus. Explore Epicor Venus for garment and apparel manufacturing.
Management needs one point where the fragmented order comes back together.
Multi-site groups often struggle because every factory closes its local period on a different operational rhythm. One site may report actual material and labor quickly while another still has open subcontracting or residual stock. If headquarters simply adds the available numbers, order margin can change significantly from one review to the next.
A practical approach is to define a consolidation status for the customer order. For example: planned, in execution, shipment estimate, and financially closed. Each factory contributes its latest evidence, but management can see which parts are still provisional.
This prevents a common mistake: comparing one order that is financially mature with another that still contains large estimates and treating the margins as equally certain.
Group visibility should expose exceptions without micromanaging every factory.
Central visibility does not mean headquarters should run every line. Local teams need freedom to manage execution. Group control should focus on exceptions that affect the customer order across sites.
Examples include material imbalance between factories, a major efficiency shortfall, quality holds, unplanned subcontracting, shipment split, premium freight or a cost variance above tolerance. These exceptions should roll up to the parent order so headquarters can decide whether the issue requires commercial action, reallocation or simply monitoring.
This model preserves local accountability while keeping the commercial promise and consolidated margin visible at group level.
Service decisions should keep their commercial consequence visible
A multi-factory group sometimes accepts extra cost deliberately to protect the buyer relationship. One site may absorb a small lot, another may ship early, or the group may move material between factories to protect a launch date. Those decisions can be commercially sensible even when they reduce the order margin.
The reporting model should therefore distinguish uncontrolled variance from approved service investment. If management knowingly spends more to protect a strategic delivery, that decision should remain visible in the order history rather than later appearing as unexplained factory inefficiency. This improves both accountability and future quotation because the business can see which customer-service patterns repeatedly create cost.
Frequently asked questions
Should each factory have its own order number?
It can have local job or allocation numbers, but they should reference the same parent customer order.
How should intercompany transfer pricing affect customer-order margin?
Keep statutory/entity reporting as required, but also maintain a group economic view that avoids double counting internal revenue and cost.
What if factories use different local currencies?
Store the original local amounts and a defined consolidation method. Margin analysis should make exchange-rate assumptions visible.
Are split shipments always bad for margin?
No. A split can protect customer service or avoid a larger penalty. The issue is making its incremental cost visible.
What is the first sign that consolidation is weak?
If the finance team cannot reconcile site-level results to the customer PO without manually rebuilding quantities and charges, the order hierarchy needs attention.