

The EMS Quote Looked Profitable. Where Did the Margin Go?
EMS margin can erode between quotation and shipment through component price changes, MOQ and excess material, actual consumption, setup, test, rework, premium freight and customer changes. Management needs a closed loop from quoted assumptions to actual job economics.
The short answer
An EMS quote can be technically correct and still lose margin after the order is won. Electronics profitability changes when component prices move, approved-source restrictions force a more expensive buy, MOQ creates excess stock, actual material consumption exceeds BOM quantity, test and rework absorb labor, delivery recovery requires premium freight, or the customer changes the product after commercial terms were set.
The answer is not simply “quote with more margin.”
The stronger model is a closed loop:
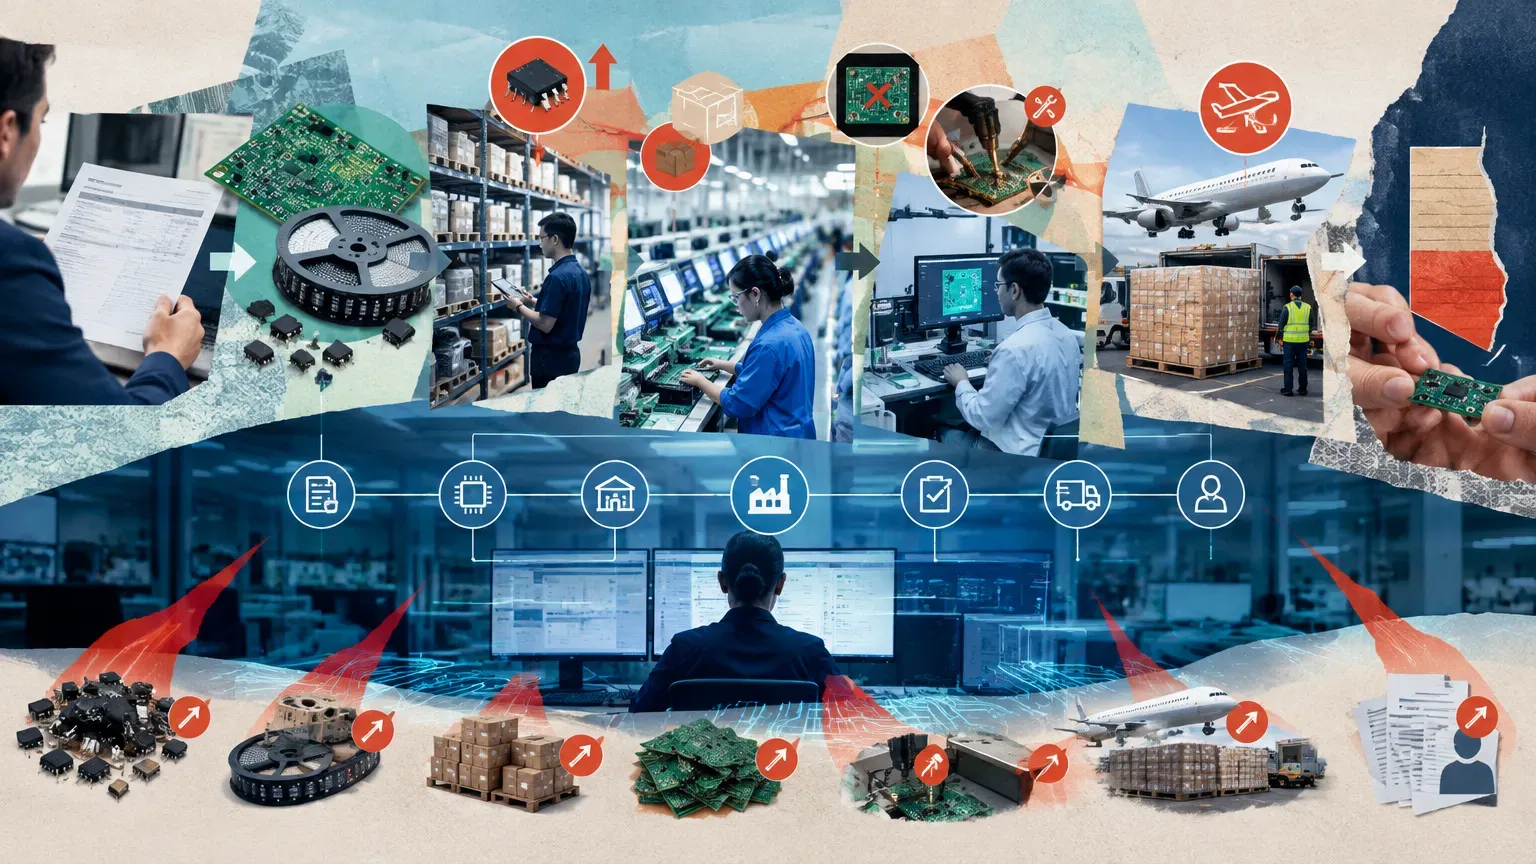
quoted assumptions → committed material → actual purchase cost → actual consumption → production/test/rework → logistics → final job cost → customer/program learning
Epicor provides the enterprise-grade ERP foundation for purchasing, inventory, work orders, costing, finance and governance. Epicor Mars adds the electronics/EMS industry layer around BOM/revision context, approved sources, barcode material usage, shop-floor execution, test, rework and traceability. Together they allow commercial assumptions to be compared with what the factory actually did.
EMS margin is exposed before production starts
A large share of electronics cost sits in material.
That means margin can begin moving while the factory is still waiting for components.
A quotation may assume:
- one approved manufacturer;
- a specific supplier price;
- a volume price break;
- normal lead time;
- no broker premium;
- standard reel quantity;
- a particular currency basis;
- normal freight.
By purchase time, some of those assumptions can be different.
The business needs to know whether the variance came from market movement, customer restriction, quantity change, sourcing choice or expedite. Quoted BOM cost is only a baseline. The RFQ BOM answers: What did we expect the material to cost?
The purchasing history answers: What did we actually commit to pay?
Those are different records serving different decisions.
If management sees only the current item cost, the original commercial assumption can disappear.
The BOM Cost Was Right at RFQ. Why Is the Actual Component Cost Higher? examines how component purchase-price variance should be separated from other job-cost changes.
MOQ turns unit cost into inventory exposure. An order may require 8,000 parts while the supplier sells only full reels of 10,000, or imposes a minimum order of 20,000.
The unused quantity is not automatically a production loss.
It might be:
- reusable common stock;
- customer-specific excess;
- forecast inventory;
- NCNR exposure;
- potential obsolete stock after ECN.
The Order Needs 8,000 Parts. Why Did You Have to Buy 20,000? focuses on how this purchasing reality should be represented commercially and operationally. Theoretical BOM quantity is not actual consumption. A BOM can require one component per assembly.
The factory may consume more than one per good finished unit because of:
- feeder setup;
- attrition;
- damaged parts;
- process scrap;
- rework;
- repair;
- samples;
- transaction error.
Not every extra component is abnormal.
The useful question is whether the variance reflects an expected process allowance or a controllable problem.
The BOM Says 10,000 Components. Why Did Production Consume 10,700? explains how to separate these causes.
Final yield can hide the cost of becoming good. A unit can eventually pass all tests and still be expensive to produce.
If it failed twice, spent an hour at diagnostics, received a replacement component and passed only after retest, final yield alone does not show the economic burden.
The Unit Passed. How Much Did Test, Retest and Rework Really Cost? looks at the labor, replacement-material and capacity cost hidden behind recovered units.
Delivery recovery can protect service and damage margin
An expedite may be absolutely justified.
The customer date may matter more than short-term cost.
But management still needs to see the recovery cost.
Typical effects include:
- broker or premium component buy;
- air freight;
- overtime;
- weekend work;
- schedule disruption;
- split shipment;
- premium outside processing.
The Customer Expedite Was Approved. Who Is Paying for the Recovery? focuses on making this incremental burden visible. Engineering change can become a commercial change. An ECN or customer revision can alter cost even when selling price stays unchanged.
The change may create:
- obsolete components;
- different approved manufacturer;
- new test;
- rework;
- additional inspection;
- new packaging;
- altered shipment plan.
The Customer Changed the Build. Did the Commercial Model Change With It? connects technical change with its commercial consequence.
Program profitability needs the whole execution history. A customer program can look attractive when standard BOM cost is compared with selling price.
The real economics may differ after:
- purchase-price variance;
- excess material;
- attrition;
- rework;
- premium freight;
- special service;
- customer changes.
Which Customer Programs Are Actually Making Money After the Factory Finishes the Job? examines how to turn those job-level effects into management insight. Protect the original commercial baseline. When a quote becomes an order, preserve the assumptions used to win it.
Useful baseline elements include:
- BOM revision;
- approved-source assumptions;
- component prices;
- exchange-rate basis where relevant;
- quantity;
- material liability assumptions;
- process route;
- test;
- expected yield;
- logistics;
- customer-supplied items.
If the baseline is overwritten by current data, the company can see the final cost but not why margin changed.
Separate price variance from quantity variance. Material can be unfavorable for two different reasons.
The business may pay more per component than quoted.
Or it may consume more components than expected.
Those require different action.
Purchase-price variance belongs to sourcing and commercial assumptions.
Consumption variance belongs to production, quality, BOM allowance or transaction accuracy.
Combining both into one “material variance” hides the cause.
Distinguish cost variance from commercial choice
Not every low-margin job is a failure.
Management may deliberately accept lower margin to:
- win a strategic program;
- enter a new customer;
- fill spare capacity;
- support a launch;
- protect a long-term relationship.
The system should still show the actual economics.
A conscious commercial decision is different from margin erosion nobody noticed. Use component-level evidence selectively. Electronics BOMs can contain hundreds or thousands of lines.
Management does not need to review every minor variance.
Focus on:
- high-value parts;
- constrained parts;
- customer-specific parts;
- large PPV;
- excess inventory;
- repeated overconsumption.
Exception-based review keeps the process practical. Treat excess material as a lifecycle decision. Excess quantity can change status over time.
At purchase it may be expected future-use stock.
After forecast reduction it may become at-risk.
After ECN it may become obsolete.
After customer cancellation it may become liability.
The same physical inventory therefore needs commercial context.
This is where enterprise inventory and customer-program context need to remain connected.
Include approved-source restrictions in cost interpretation. A buyer may be criticized for paying more than market price even though the cheaper part was not customer-approved.
Purchase-price analysis should compare against executable alternatives.
The lowest online price is not automatically the relevant benchmark.
Epicor Mars-specific source context helps explain why the actual component cost was commercially necessary. Use actual material transactions to improve costing. Barcode-driven material issue and production consumption can create a clearer actual-cost trail.
Where the product requires traceability, the same scan can support both genealogy and consumption evidence.
This reduces the need to reconstruct usage later.
The exact transaction design should fit the factory, but the principle is valuable: capture actual material movement close to where it occurs.
Measure rework as an operating path
Rework should not disappear inside normal labor.
If repeated defects create meaningful diagnostics and repair effort, capture the burden at a useful level.
This does not require time-sheet bureaucracy for every technician minute.
It requires enough evidence to know which products, defects or customers create recurring recovery work. Connect quality cost with job cost. Scrap, rework and retest are quality effects and financial effects.
Epicor Mars can capture the execution reason.
Epicor can carry inventory, labor and financial context.
Together they help management answer a more useful question:
Which quality problems are materially changing job margin? Capture expedite cost at the event. Premium freight and emergency buying are easiest to understand when linked to the order or recovery decision that caused them.
If the cost is posted later to a broad freight or purchasing account, the customer-program impact becomes invisible.
Use practical references that connect recovery cost to the affected job or program.
Treat customer change as a controlled economic event. The technical change process should identify whether the original commercial basis still holds.
Questions can include:
- Does material become obsolete?
- Does new material cost more?
- Is additional test required?
- Is rework needed?
- Does the delivery plan change?
- Is premium freight created?
The answer does not always require a customer charge.
Management may choose to absorb it.
But absorption should be deliberate. Build a quote-to-actual bridge. For important jobs, start with quoted margin and bridge to actual:
1. component price variance;
2. excess/MOQ exposure;
3. material usage variance;
4. labor/setup variance;
5. test/rework;
6. subcontract variance;
7. expedite/logistics;
8. customer changes;
9. other approved commercial decisions.
This turns “margin was lower” into a set of actionable causes.
Use repeat programs to improve the next quote
EMS programs often repeat.
That creates a valuable learning loop.
The next quotation can use:
- actual component buy history;
- real consumption;
- test time;
- rework rate;
- expedite pattern;
- excess inventory history.
Do not copy the old price blindly.
Use the old execution evidence to improve the new commercial assumptions. Use profitability variance as a cross-functional language. Finance may describe a job as margin variance while purchasing sees a premium buy, production sees extra consumption, and quality sees rework. Use a small shared cause taxonomy so these are recognized as parts of the same economic story. This reduces debates over whose number is correct and helps management identify the operating decision that needs to change.
Protect customer-specific cost rules. Some customers supply components, reimburse excess material, pay NRE separately or accept premium freight under defined conditions. Program profitability should respect these commercial rules. The same physical cost can have a different economic effect depending on whether the customer bears it, the EMS provider absorbs it, or the cost is shared. Use profitability review to improve—not punish—execution. If every variance review becomes a search for blame, teams will defend their numbers instead of exposing the real cause. The strongest review asks whether the original assumption, purchasing action, process standard or customer term needs to change. Accountability still matters, but the purpose is a better next decision.
Use job-cost variance before the month-end summary
Waiting until month-end can make the numbers accurate but the operational memory weak. For material or margin exceptions above a threshold, review the job while purchasing, planning and production still remember what changed. Early review makes it easier to distinguish a sourcing decision, customer change or execution problem before the story is reduced to a single financial variance. Keep commercial recovery separate from operational recovery. A factory may recover the customer date successfully while the commercial team still needs to decide whether incremental cost is absorbed, shared or charged. Do not treat operational success as financial closure. The shipment can be on time and the program can still lose margin if premium buys, overtime or rework are never connected back to the commercial decision.
Connect profitability review to sales terms. Operational evidence is most useful when it can change the next commercial agreement. If one customer repeatedly creates NCNR exposure, short-notice expedites or unrecovered ECN cost, the account team can use actual history to discuss lead times, forecast liability, change terms or service charges. The goal is not to turn every issue into a surcharge. It is to align the commercial model with the service and supply-chain model the customer actually uses. Protect the difference between accounting close and operational learning. Financial close determines the recognized result. Operational review explains why the result happened. Keep both. Finance may book purchase-price variance or scrap in standard categories, while Epicor Mars execution can identify the component, work order, defect or expedite event behind it. That combined view gives management a bridge from accounting outcome back to the physical process.
What management should measure
Useful indicators include:
- quote-to-actual material cost variance;
- component PPV;
- excess/NCNR inventory by customer;
- actual consumption versus BOM;
- rework and retest burden;
- premium freight and expedite cost;
- cost created by customer/ECN change;
- jobs below quoted margin;
- repeat programs with recurring variance;
- customer/program contribution after actual execution.
The goal is not to turn operations into accounting.
The goal is to make operational causes visible in the economics.
A practical monthly profitability review
Choose a small number of jobs with the largest difference between quoted and actual margin.
For each job, classify the largest cause.
Then ask:
- Was the quote assumption wrong?
- Did the customer change the requirement?
- Did sourcing conditions change?
- Did the factory consume more than expected?
- Did quality/rework increase cost?
- Did delivery recovery create premiums?
- Is the cause recurring?
Only recurring causes should automatically change future standards.
One-off events should remain visible without distorting every future quote.
Where Epicor Mars fits in quote-to-actual profitability
For quote-to-actual profitability, the key system-design question is how to keep enterprise control and electronics-specific execution on the same operating thread. Epicor provides the enterprise-grade ERP foundation for customer orders, purchasing, inventory, planning, costing, finance, approvals and governance. Epicor Mars extends that foundation with the EMS industry context needed at the point of work, including material identity and readiness.
That connection is directly relevant to The EMS Quote Looked Profitable. Where Did the Margin Go?. EMS margin can erode between quotation and shipment through component price changes, MOQ and excess material, actual consumption, setup, test, rework, premium freight and customer changes. Management needs a closed loop from quoted assumptions to actual job economics. When the Epicor Mars execution record stays tied to the Epicor work order, material and customer context, management can compare the business commitment with what the factory actually executed without maintaining a second source of truth.
For quote-to-actual profitability, that complementary positioning is the point: Epicor remains the enterprise-grade foundation, while Epicor Mars adds the EMS workflows needed to make this particular control operational on the factory floor. Explore Epicor Mars for electronics manufacturing.
Frequently asked questions
Is standard cost enough to understand EMS profitability?
It is useful for control, but quote-to-actual review needs the real purchase, usage and execution effects that changed the job.
Should excess MOQ inventory be charged to the first order?
Not automatically. The treatment depends on reuse probability, customer agreement and material risk.
Does every rework minute need to be recorded?
No. Capture enough to understand material recurring burden without creating excessive transaction overhead.
Should customer expedites always be charged?
That is a commercial decision. The incremental cost should still be visible.
Why is Epicor + Epicor Mars useful for profitability?
Epicor carries the enterprise financial and transaction backbone; Epicor Mars adds the EMS-specific execution evidence that explains why actual cost changed.